
MEET THE AGENCY
Inside Story
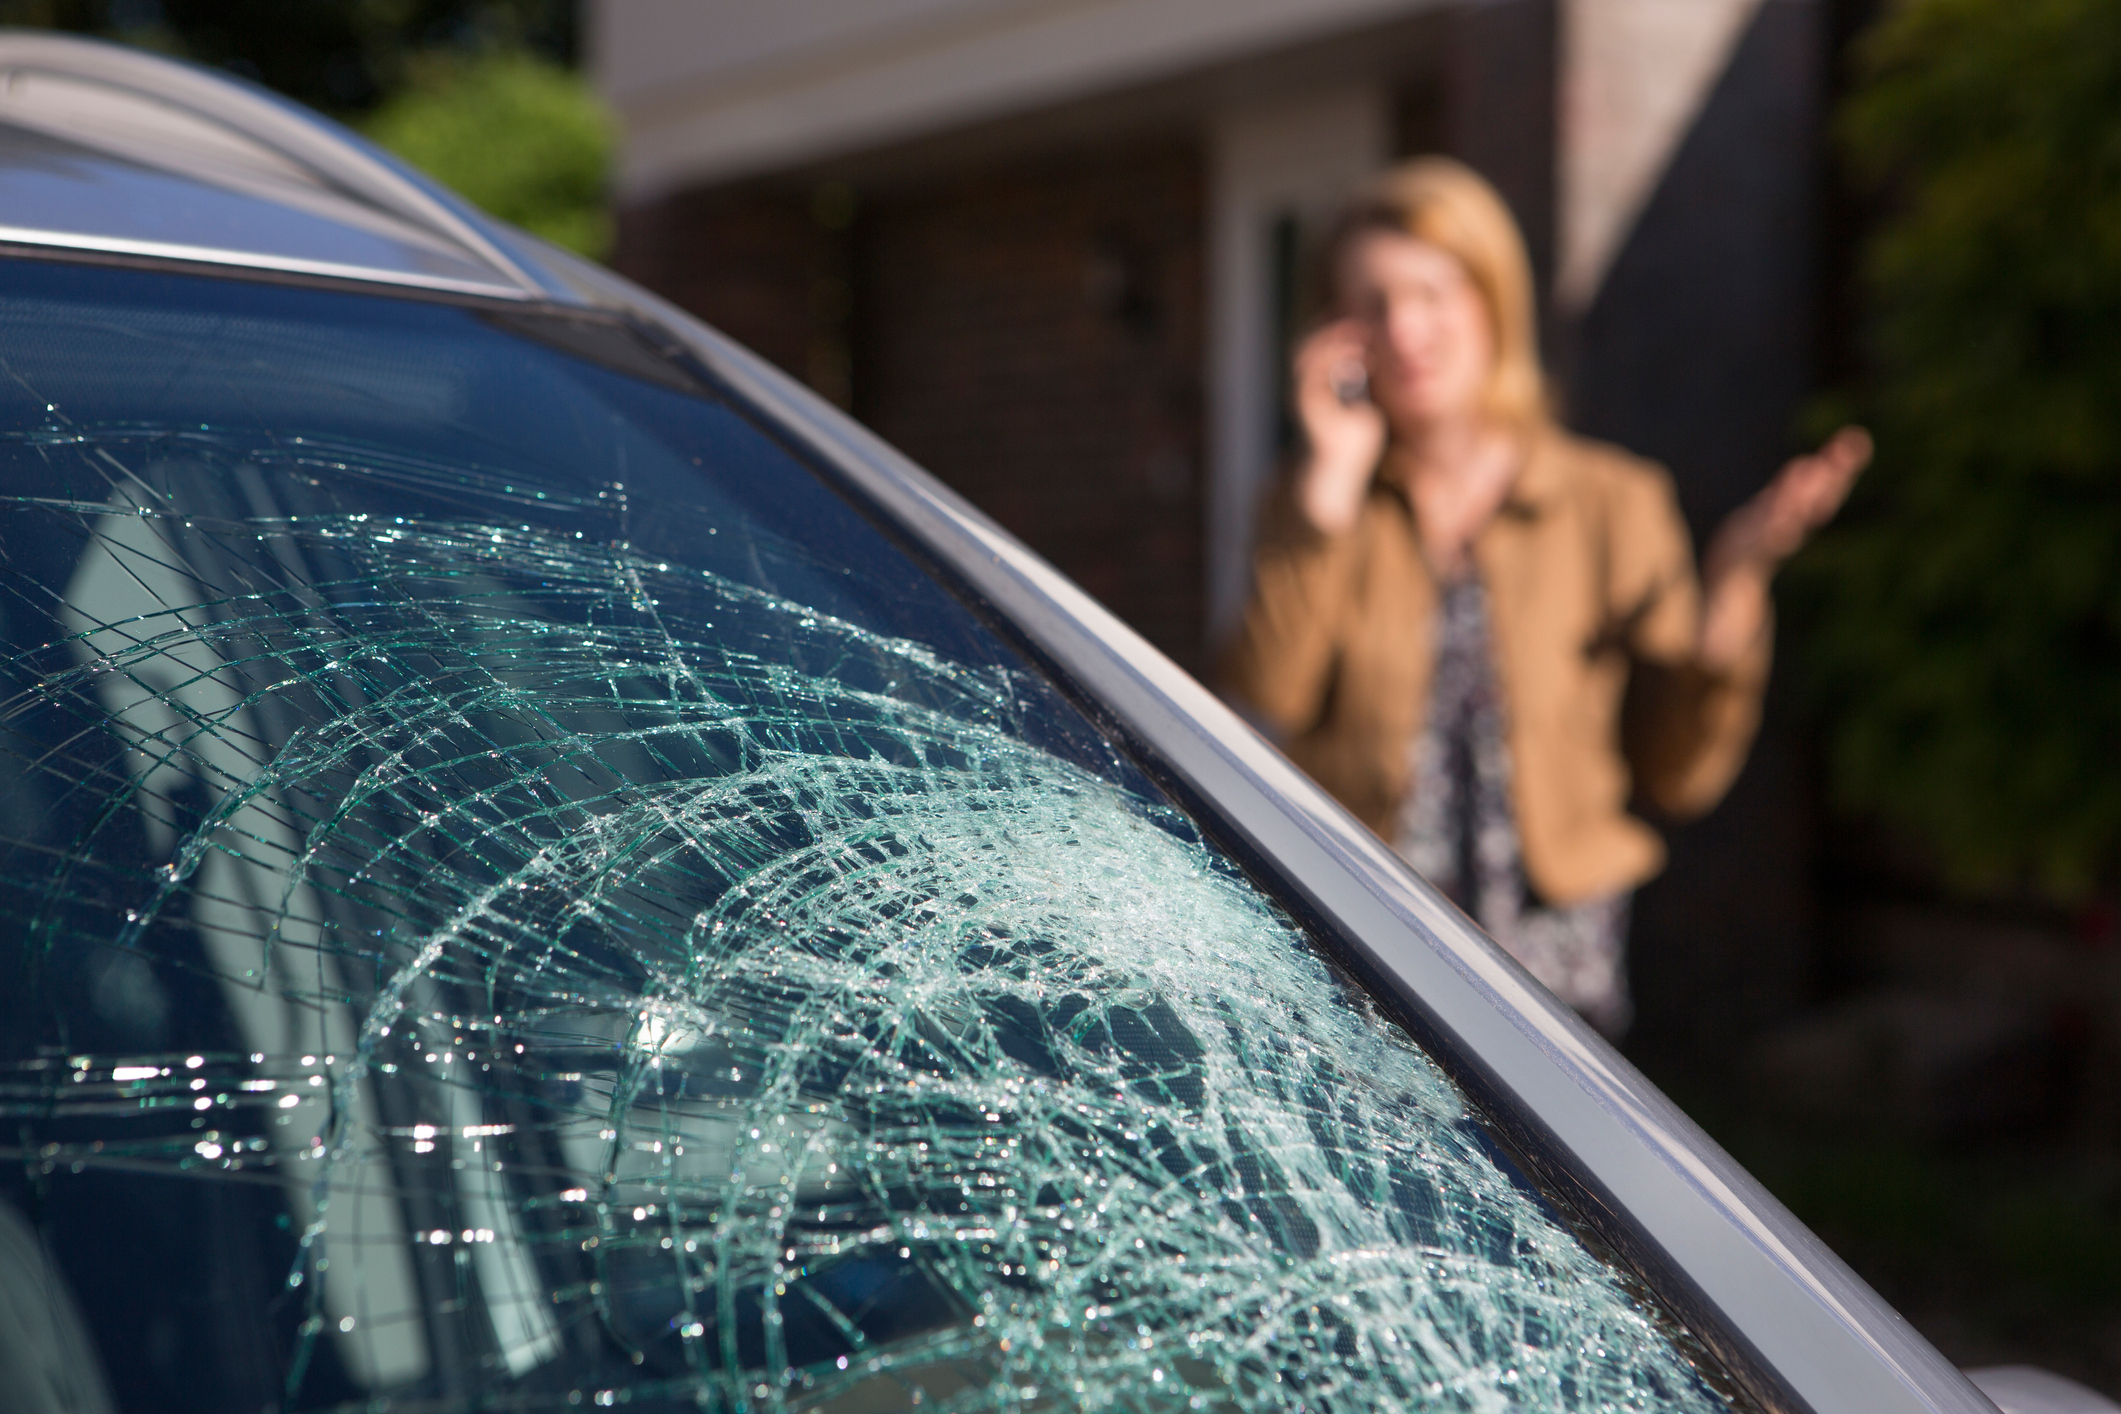
Quick answer: A single windshield claim generally won't raise your car insurance rates. Windshield damage is typically covered under comprehensive (called Other Than Collision Coverage at Indiana Farm Bureau Insurance) coverage, which insurers generally treat differently from at-fault accident claims. At Indiana Farm Bureau Insurance, we generally waive the deductible for windshield repairs that can be fixed rather than replaced (certain limitations apply).
A rock flies off a truck on I-65. A hailstorm rolls through Tippecanoe County. A tree branch drops in your driveway overnight. However, it happens, you're staring at a crack in your windshield and wondering about two things: Is this covered? Will filing a claim make my insurance go up?
Both are fair questions. Here's what Indiana drivers should know about windshield claims, what they cost, and when you should consider paying out of pocket.
In most cases, no. A single glass claim typically won't cause a rate increase on its own.
Windshield damage is generally covered under comprehensive coverage (called Other Than Collision Coverage at Indiana Farm Bureau Insurance). This is the part of your policy that may help handle things outside your control: weather, falling objects, animal strikes, theft, and vandalism. Because windshield damage is rarely the result of how you drive, insurance companies generally don't weigh it the same way they might weigh an at-fault collision.
That said, your premium is based on a combination of factors, not just your claims history. When your insurer periodically reevaluates your rate, they consider your driving record, the number and type of recent claims, your location, your vehicle, and more. A single glass claim in an otherwise clean history is typically less likely to move the needle. Multiple claims in a short window, glass or otherwise, might.
The bottom line: Strongly consider repairing or replacing a damaged windshield. A damaged windshield is a safety issue, and one glass claim generally won't drastically change what you pay.
At Indiana Farm Bureau Insurance, windshield damage falls under Other Than Collision Coverage. Here's how typically it works:
Repairable damage (chips, small cracks): If the windshield can be repaired rather than replaced, we generally waive the deductible. You may pay nothing out of pocket for the repair (certain limitations apply).
Replacement needed: If the windshield has to be fully replaced, your deductible applies. Your policy may help cover the remaining cost above the deductible.
Lowest available deductible: Our lowest Other Than Collision Coverage deductible is $100.
This deductible waiver that may apply for repairs is a meaningful benefit. Many windshield cracks start as small chips that can be repaired for$80-$150 or more, if they're caught early. Waiting until the crack potentially spreads across the glass often means a full replacement, which costs more and triggers the deductible.
Not sure what coverage is on your policy? You can review your policy online or reach out to your local Indiana Farm Bureau Insurance agent for a walkthrough.
This is the real question most people are asking. The answer depends on two numbers: the cost of the repair and your deductible. Typically, you should contact your insurance company to file a claim and learn more about your options. Remember, once you file a claim, you can ask your claims representative to close it later if you decide to pay out of pocket.
The windshield needs full replacement and the cost exceeds your deductible by a significant margin.
Multiple glass panels are damaged (side windows, rear glass).
You have Indiana Farm Bureau Insurance's Other Than Collision Coverage and the damage is repairable. The deductible is generally waived, so the repair may cost you nothing.
The repair cost is less than your deductible.
The cost is close to your deductible, so the insurance payout would be minimal.
You've already filed several claims recently and want to keep your claims history clean.
A rock chips your windshield on State Road 37. A glass shop confirms it can be repaired for $89. You have Indiana Farm Bureau Insurance's Other Than Collision Coverage → deductible typically waived for repairs → you may pay $0. File the claim.
Hail damages your windshield beyond repair. The replacement quote is $643, and your deductible is $250 → insurance typically covers $393 → filing may save you $393 when it comes to covering the damage. File the claim.
A small crack spreads to about 6 inches. Replacement quote is $310, and your deductible is $500 → insurance would typically pay $0 because the cost is below your deductible → pay out of pocket. Reach out to your claims adjuster to close your claim if you filed one.
These examples are for illustrative purposes only. Actual costs depend on your vehicle, glass type, and policy terms.
Costs vary depending on your vehicle make and model, the type of glass, and whether the windshield includes sensors or cameras for an Advanced Driver Assistance Systems (ADAS). Here's a general range:
Service | Typical Cost Range |
Windshield chip repair | $80 – $150 or more |
Windshield replacement | $280 – $1,000 or more |
Vehicles with rain sensors, lane-departure cameras or heads-up displays built into the windshield typically cost more to replace. If your car has ADAS features, the windshield may need to be recalibrated after replacement. That’s an additional step that may add to the total cost.
Don't ignore it. Small chips often spread, especially in Indiana's freeze-thaw cycles. What could be a $0 repair today might become a more costly replacement next month.
Don't try a DIY repair kit on a large crack. These kits may work for tiny chips at best. A poor repair can compromise the windshield's structural integrity and may void your coverage for a future claim on the same damage.
Don't assume you're not covered. If you have Other Than Collision Coverage (also known as comprehensive), your windshield is likely covered. Check your policy before paying out of pocket.
Don't delay because you're worried about your rate. Typically, a single glass claim rarely affects your premium, and driving with a damaged windshield is a safety hazard.
Whether or not you file a glass claim, these strategies may help offset premium changes over time:
Fix chips early. A repair is generally cheaper than a replacement, and Indiana Farm Bureau Insurance typically waives the deductible for repairable damage (certain limitations apply). Early action may help you save money and avoid a larger claim.
Bundle your policies. At Indiana Farm Bureau Insurance, you can save up to 18% on auto insurance and up to 20% on your home insurance premium when you insure both with us.
Maintain a clean driving record. Your driving history is among the biggest factors in your premium. Safe driving habits may pay off at renewal time. (Related: How long does a speeding ticket stay on your record in Indiana?)
Take advantage of discounts. Indiana Farm Bureau Insurance offers a Paperless Discount, DriveTrend® Discount, Full Payment Discount, and Multi-Car Discount, among others. Ask your agent which ones may apply to your policy.
Review your deductible. A higher deductible often lowers your premium but may mean more out-of-pocket cost if you file a claim. Find the balance that works for your budget.
File glass claims sparingly. You have insurance to help protect you when you need it, for covered losses with significant damage, file the claim. But for minor repairs you can afford, consider paying out of pocket. It can help keep your claims record clean.
Not sure what glass coverage you have?
Your local Indiana Farm Bureau Insurance agent can review your policy, explain your deductible options and help you select the appropriate coverage for your vehicle.
If you have comprehensive or Other Than Collision Coverage on your policy, windshield replacement is generally covered after your deductible. If the windshield was damaged in a car accident, it may be covered under your Collision Coverage instead. Liability-only policies generally do not cover windshield damage to your own vehicle.
Typically, yes. At Indiana Farm Bureau Insurance, windshield damage from rocks, hail, falling objects, animals, and other non-collision events is generally covered under Other Than Collision Coverage. If the damage can be repaired, we typically waive the deductible (subject to certain limitations). If replacement is needed, your deductible applies.
In many cases, yes. A single comprehensive glass claim with an otherwise clean claims history is generally unlikely to trigger a significant rate increase. However, insurers reevaluate your premium periodically based on multiple factors including claims history, driving record, and location. Filing many claims in a short period, glass or otherwise, could affect your rate at renewal.
It depends on your policy. At Indiana Farm Bureau Insurance, the lowest available deductible on Other Than Collision Coverage is $100, with several higher options. Generally, a higher deductible means a lower premium. For repairable windshield damage, Indiana Farm Bureau Insurance typically waives the deductible entirely (certain limitations apply).
Generally, compare the replacement cost to your deductible and consider your options. If the cost is well above your deductible, filing a claim may save you money when it comes to covering the damage. If the cost is close to or below your deductible, paying out of pocket may be the better choice for you. For small chips that can be repaired, Indiana Farm Bureau Insurance generally waives the deductible (subject to certain limitations), so filing often makes sense regardless.
Filing a single glass claim generally will not cause your insurer to drop you. Insurers consider many factors when evaluating a policy, and one comprehensive claim is typically not cause for non-renewal. However, a pattern of frequent claims across multiple coverage types could prompt a review.
Ideally, yes. A cracked windshield may compromise your vehicle's structural strength and can obstruct your view. In Indiana, law enforcement can cite you if a crack impairs your ability to see clearly while driving. Small chips can also spread quickly due to temperature changes, turning a potentially low-cost repair into a full replacement. (Related: Does car insurance cover a cracked windshield?)
Contact Us
*Securities & services offered through registered representatives of FBL Marketing Services, LLC, 225 South East Street, Indianapolis, IN 46202, 317-692-7628, Member SIPC. FBL Marketing Services, LLC, is not affiliated with Indiana Farm Bureau, Inc. or United Farm Family Life Insurance Company.
© 2026 Indiana Farm Bureau Insurance. All Rights Reserved. Farm Bureau, FB, and
the national Farm Bureau logo are trademarks of the American Farm Bureau Federation.


